Options backtester: test an intraday NIFTY strategy on recorded sessions
Run a multi-leg options strategy across past sessions, with your entry and exit rules and trading costs, and see the equity curve, drawdown and month-by-month results.
What is an options backtester?
You describe a strategy once: its legs, when it enters, when it exits and what stops it out. The backtester then runs it on every session in the date range you choose, one day at a time, and reports what each day would have made or lost. The question it answers is not whether a structure works on one memorable day, but how it behaved across many ordinary ones.
What rules can I set?
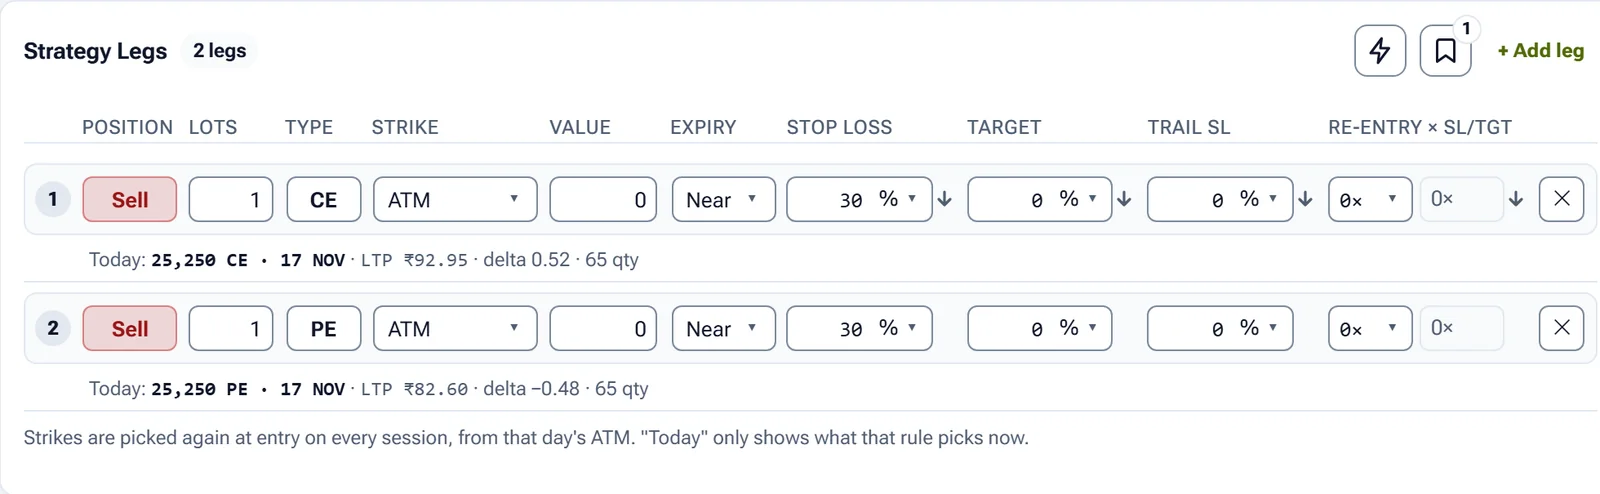
- Legs. Calls, puts and futures, bought or sold, with the lots for each.
- Strike selection. At the money, a number of strikes out of or in the money, a percentage away from spot, the strike with the closest premium to a target, a premium above or below a level, or a target delta.
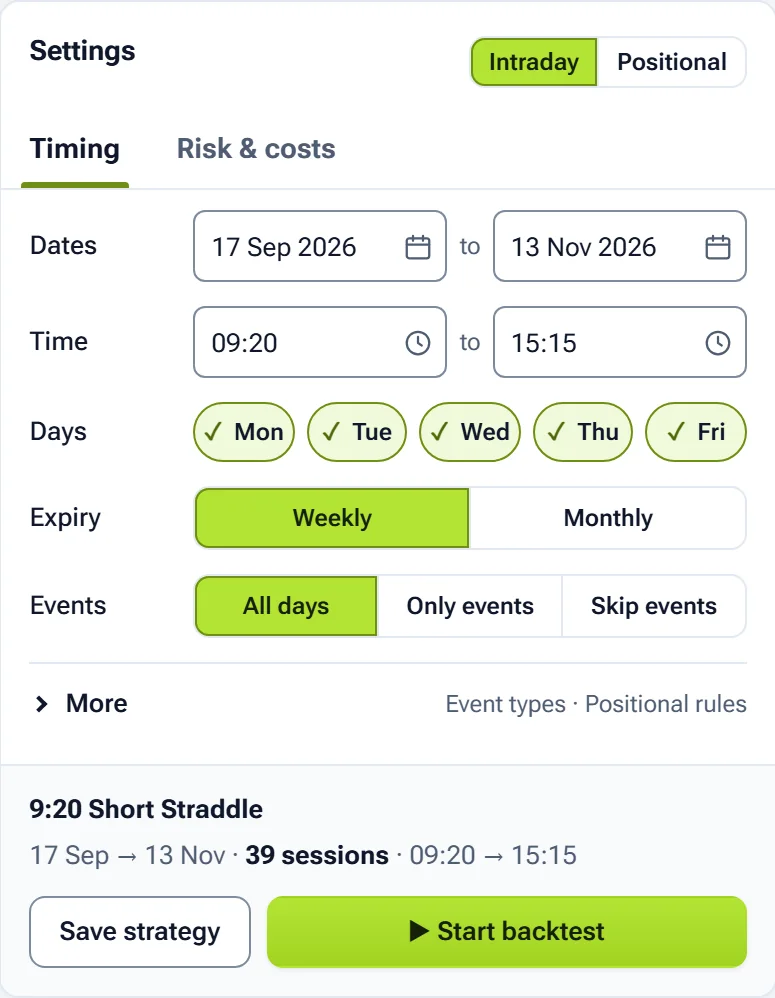
- Timing. An entry time, an exit time, and the weekdays to trade on.
- Stops and targets per leg. A stop loss, a target and a trailing stop, measured in premium points, premium percent, or points or percent of the underlying.
- Stops for the whole strategy. An overall stop loss and an overall target on the combined position.
- Adjustments. Rolling the short leg when spot moves by a set amount.
- Costs. Brokerage, statutory charges and slippage, from a no-cost theoretical run to a realistic one, so the result is what would have been kept rather than what was gross.
What does a backtest report show?
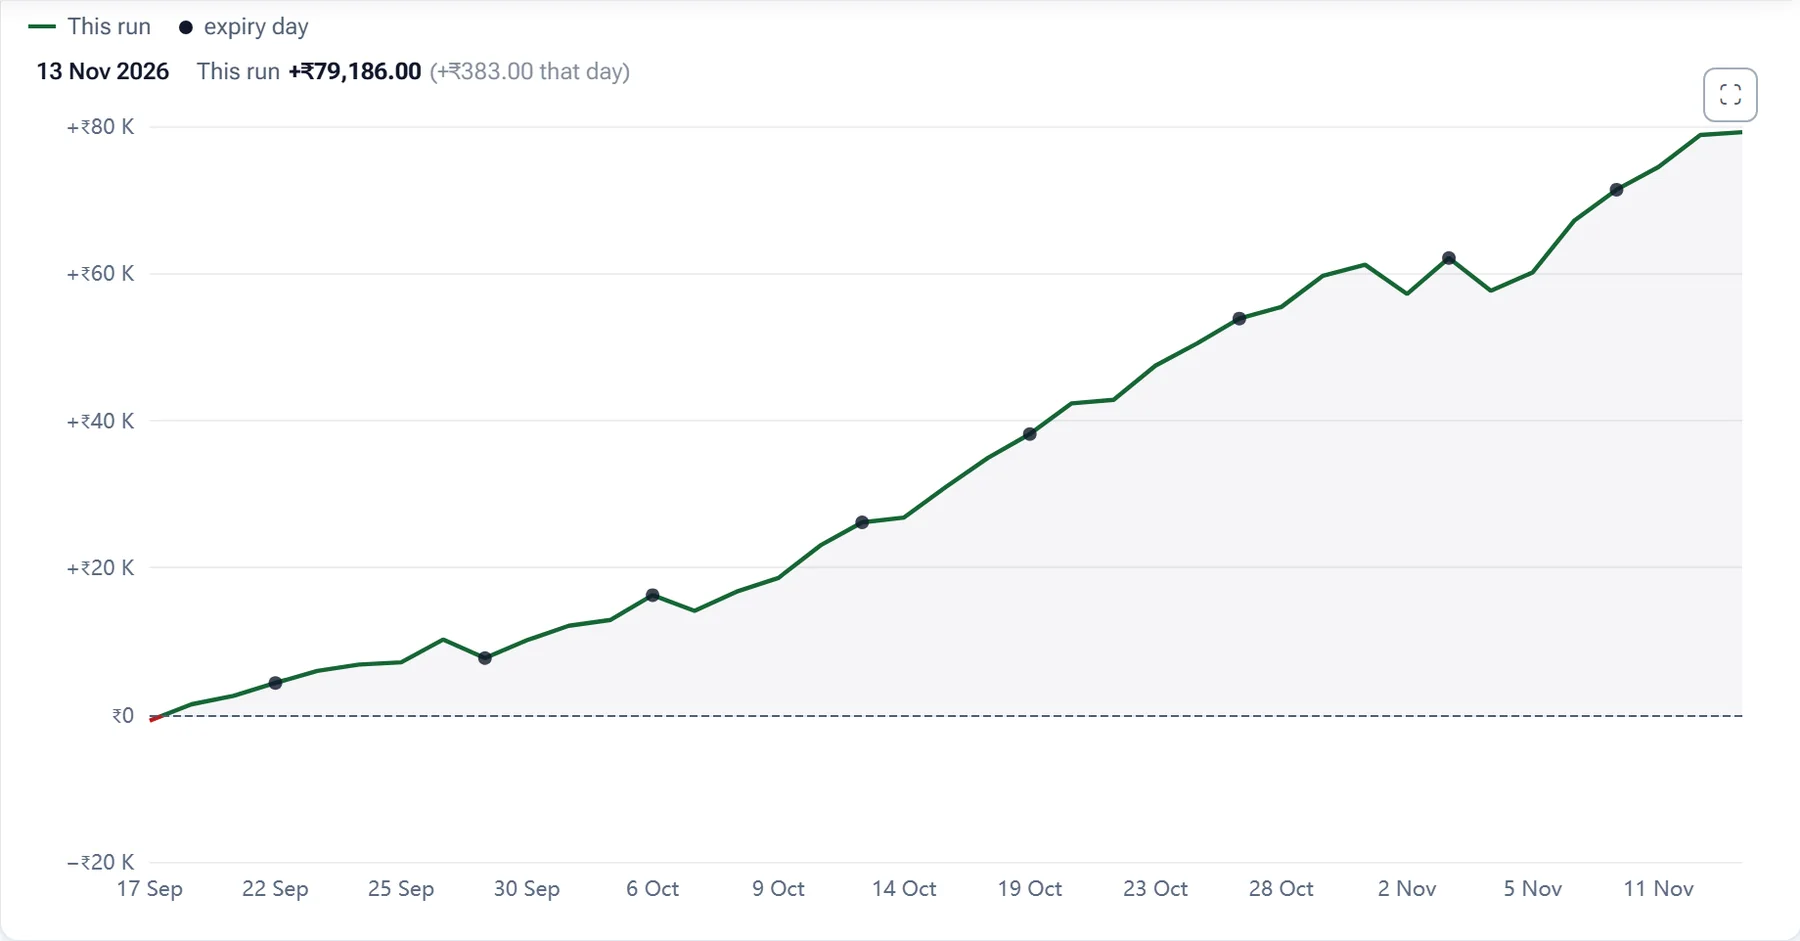
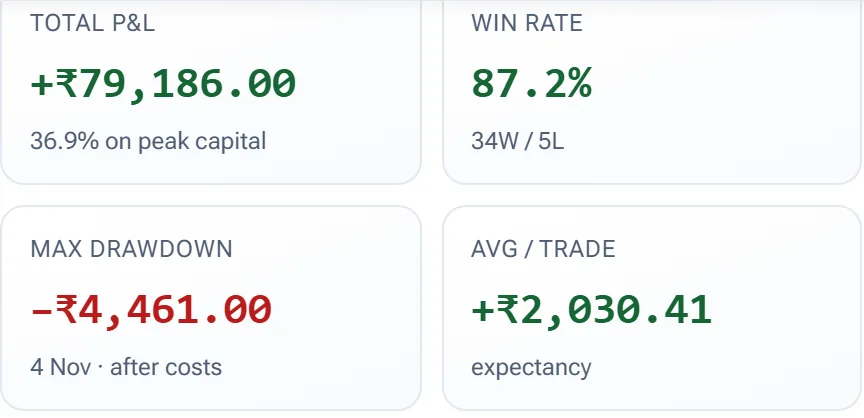
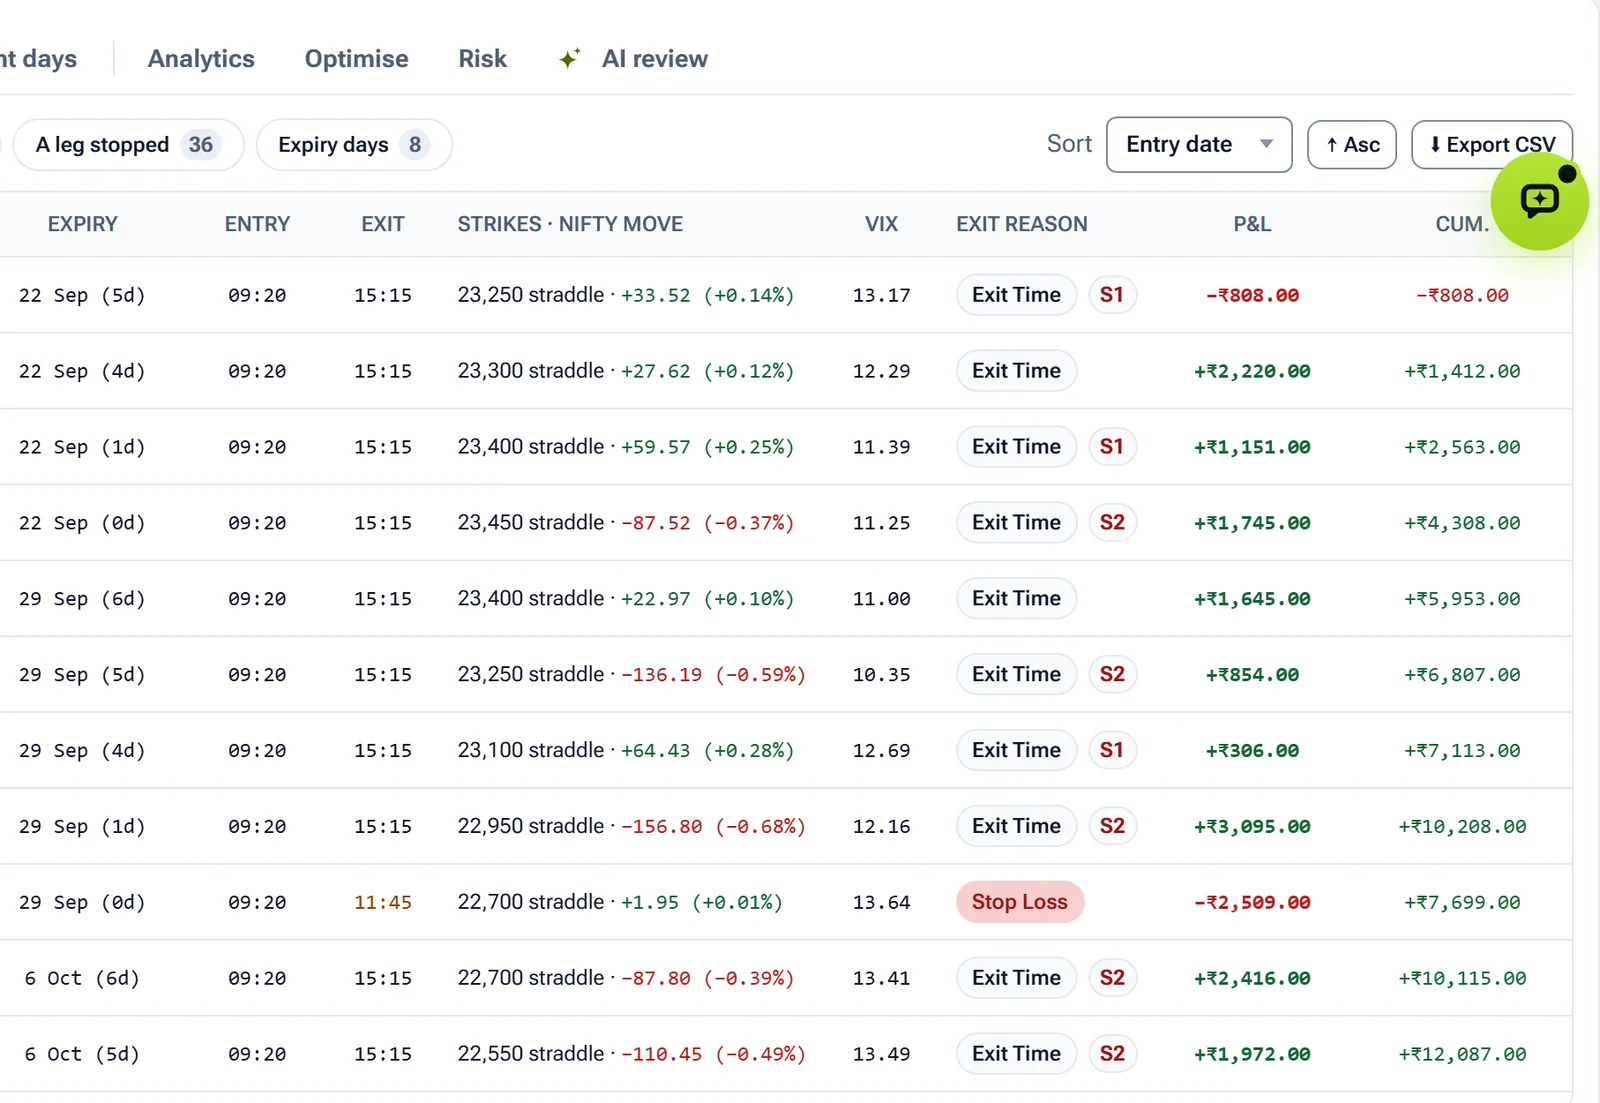
An equity curve of cumulative P&L, the drawdown beneath it, and monthly and year-wise returns. Summary measures include the return against the worst drawdown, the profit factor, an annualised Sharpe ratio and the expectancy per trade. A full report lists every day and every leg: when it entered, at what price, and why it exited.
Where do the option prices come from?
Where a session has been recorded, the backtest uses the option premiums that actually printed that day, so a stop fills against a real price rather than a model's. Where no recording exists, it falls back to modelled premiums and says so, per day and per leg, so a result built on a model never passes for one built on the market. The same recorded sessions can be watched minute by minute in Session Analysis.
What can a backtest not tell you?
A backtest describes the past under the rules you gave it. It cannot know how fills behave at your size, whether the conditions it ran through will return, or how a rule tuned to those sessions will do on the next ones. A strategy adjusted until its backtest looks perfect has usually learned the past rather than anything about the future. Read the drawdown and the worst months before the total.
Backtester questions
Can I backtest options strategies on NIFTY?
Yes. The backtester runs multi-leg NIFTY option strategies across a range of past sessions, with your strike selection, entry and exit times, stops, targets and trading costs, and reports the equity curve, drawdown and monthly results.
Does the backtest use real option prices?
Where a session has been recorded, it uses the premiums that actually traded that day. Where none was recorded, it falls back to modelled premiums and labels those days and legs, so the two are never mixed silently.
Are brokerage and taxes included in the results?
They can be. Brokerage, statutory charges and slippage are set before the run, from none at all for a theoretical result to a realistic set, and the report shows what the costs took.
Is a good backtest a reason to trade a strategy?
No. A backtest shows how rules would have behaved on past sessions; it does not predict the next ones, and a strategy tuned until its history looks perfect often fails on new data. It is a tool for understanding risk, not a recommendation.
Start free
Educational analytics only: not investment advice. You are responsible for your own trading decisions.