Expected move: the range NIFTY options are pricing to expiry
How far is the market expecting the index to move by expiry? This chart answers it two ways, from the straddle and from implied volatility, and then checks the answer against what happened.
- What it is
- A range chart of how far the index is priced to move by expiry, from the straddle and from implied volatility, with a record of actual moves.
- Data it uses
- NSE option chains for the next six expiries (ATM straddle, ATM IV, parity spot); recorded closing ATM IV and index closes for the record.
- Covers
- NIFTY, BANKNIFTY, FINNIFTY, MIDCPNIFTY and NIFTY NEXT 50
- Updates
- Live through the session; the record adds a session after each close (recorded since 31 Jul 2026)
What the chart shows
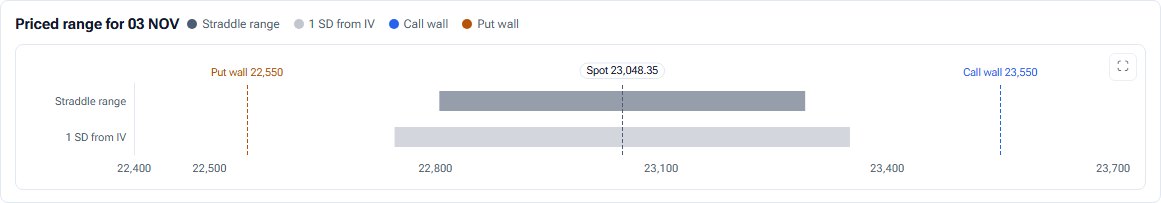
- Priced range: horizontal bars for the straddle range and the one-standard-deviation IV band on an index-level axis, with spot and the call and put walls marked.
- Priced against actual: for each recorded session, the move that was priced beside the move that happened, green when the index rose and red when it fell.
- Cards: the expected move, its range, the ATM straddle, the 1 SD band, and how many past moves stayed inside it.
How it is worked out
Straddle range = spot ± the ATM straddle premium. 1 SD band = spot × ATM IV × √(calendar days to expiry ÷ 365), roughly a 68% range. Each expiry uses its own spot from put-call parity.
How to read it
This is the size of move already in the price. If the index stays inside the 1 SD band much more often than about two times in three, options have been priced rich.
Controls
- Session: today, or a stored past session
- Expiry: any of the next six
- History: one day, or to expiry
Keep in mind
Neither range is a forecast or a target, and neither says which way. The record uses closing ATM IV recorded since 31 Jul 2026, so it is still short and says little either way yet.
Expected move questions
How is the expected move calculated?
Two ways: spot plus or minus the at-the-money straddle premium, and spot times ATM implied volatility times the square root of days to expiry over 365.
How often does NIFTY stay inside the expected move?
The scorecard counts it from recorded sessions. A one-standard-deviation band should hold about 68% of the time if options are fairly priced.
Does it say which direction?
No. Both ranges are symmetric around spot.
Related tools and guides
Straddle Premium
The at-the-money call plus put premium through the session with its VWAP, the auto-ATM line, time value and decay per hour, from NSE minute bars.
IV Skew
Implied volatility at every strike for calls and puts, the 5% put-call skew, and ATM IV across the next six expiries.
Max Pain
Total rupee pain to option buyers at every strike, the max pain strike against spot, max pain for the next four expiries and session by session.
All Pulse charts
Every chart in Pulse with a screenshot and what it tells you.
Educational analytics only: not investment advice. You are responsible for your own trading decisions.