Multi-strategy Backtest

Test several strategies together, as one book.

Put up to 10 strategies in a portfolio and run them on the same past sessions. You see what the book made each day, and what each strategy added to it, on recorded prices only.

New here? Start free, no card needed.

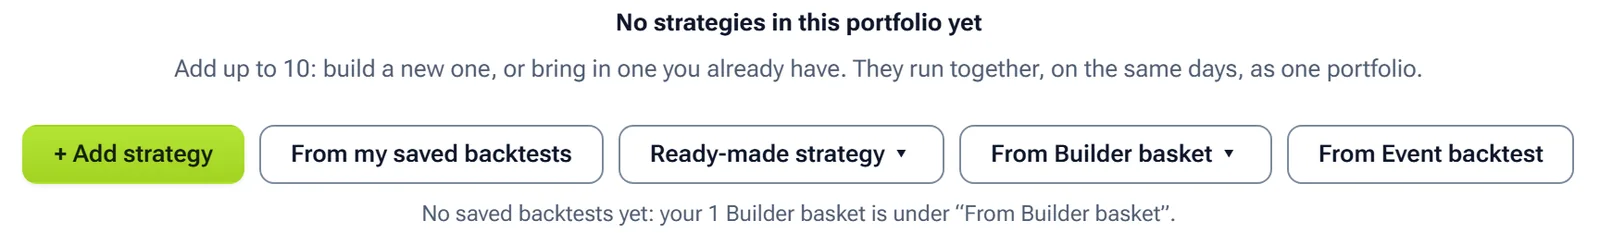
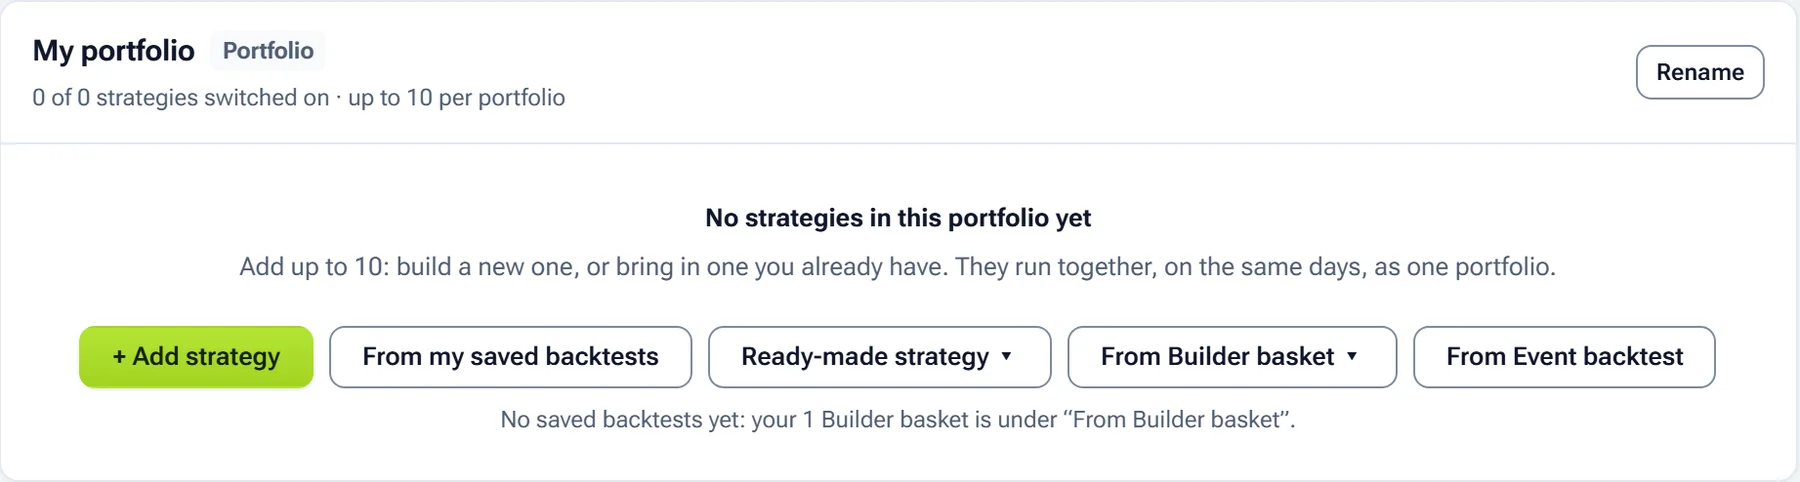
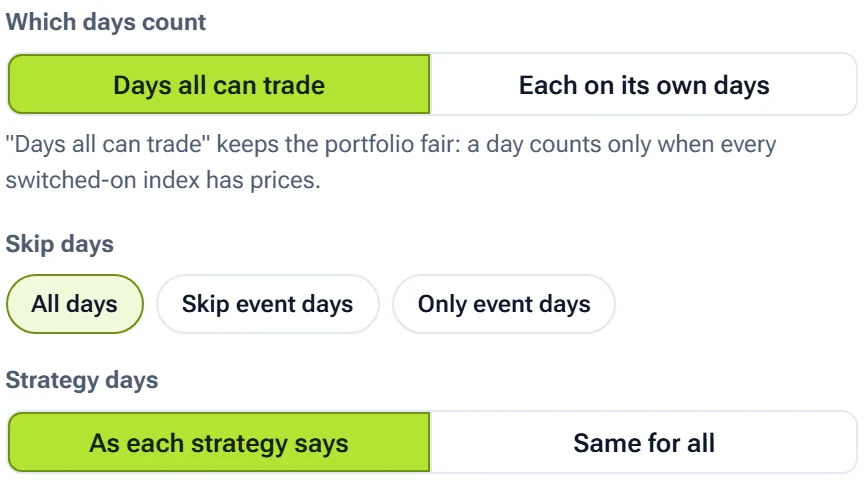
1 credit per runMy portfolio card, empty, with Add strategy, From my saved backtests, Ready-made strategy, From Builder basket and From Event backtestWhich days count: Days all can trade or Each on its own days, with skip days and strategy days choices

Three steps to a portfolio test

Fill the portfolio, decide which days count, then run it once. Each strategy keeps its own legs, times and mode.

Fill the portfolio

Build a strategy from scratch or bring one in from a saved backtest, a ready-made strategy, a Builder basket or an Event backtest. Edit one in a drawer with the same controls as Backtest.

  • Up to 10 strategies per portfolio
  • Switch each on or off, set its lots, duplicate it
  • Intraday and Positional can be mixed
Buttons to add a strategy: new, from saved backtests, ready-made, from a Builder basket or from an Event backtest

Decide which days count

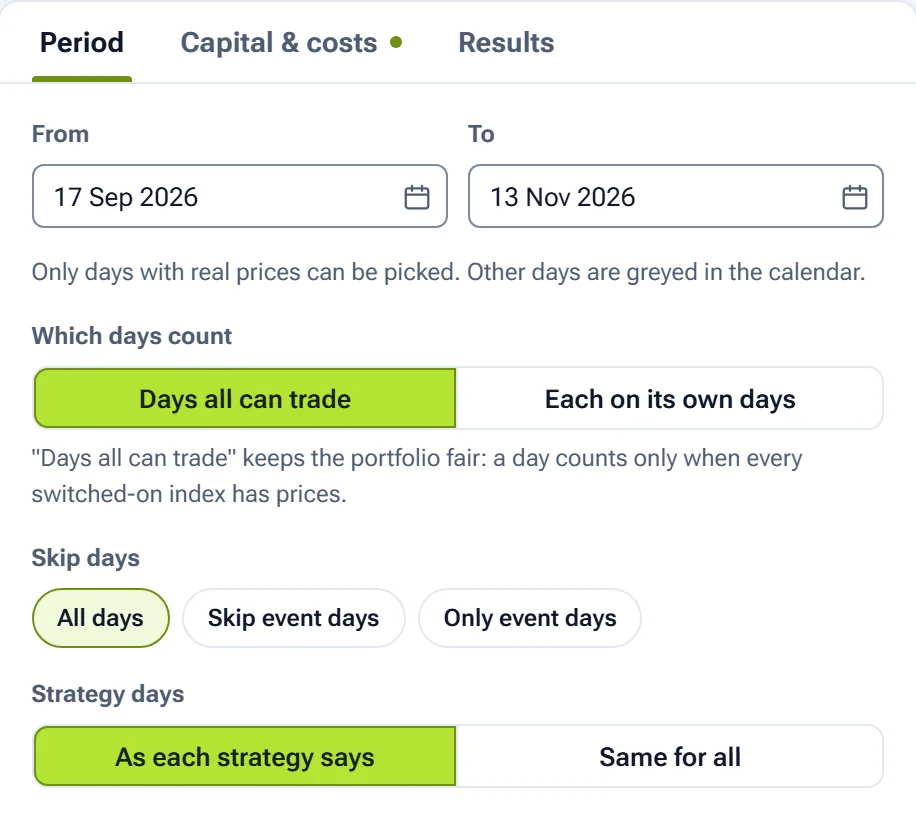
By default a day counts only when every switched-on index has prices, which keeps the comparison fair. Or let each strategy trade on its own days.

  • Only days with real prices can be picked
  • All days, skip event days or only event days
  • Each strategy's weekdays, or the same for all
Period tab: From and To dates, Which days count, Skip days and Strategy days

Set capital and costs, then run

Set the capital, how each strategy is sized, slippage and charges. One run costs one credit, however many strategies are in it.

  • Size by lots, equally, or by weights
  • Save the portfolio and reload it from Saved
  • Compare with your last run
What this test covers, with Save portfolio and Start backtest, and the note: 1 credit per run, however many strategies

What the combined run shows

One equity curve for the book

Portfolio P&L by day, its drawdown, a P&L calendar, results by weekday and each strategy's contribution.

Each strategy's share

What each one made, and what the book's total and drawdown would be without it.

Correlation between strategies

Whether the strategies win and lose on the same days, or offset each other.

Inside each day

The combined mark-to-market through each session, so the day's worst and best points show, not only the close.

Open Multi-strategy Backtest on today's data

NSE data, 15 minutes delayed. Analytics, not advice.

Open Multi-strategy Backtest

Start free

Educational analytics only: not investment advice. You are responsible for your own trading decisions.