Delta exposure (DEX): estimated dealer delta and futures hedging
If today's option trades left dealers longer or shorter delta, they hedge with futures. Delta exposure estimates that position strike by strike and turns today's change into a futures figure.
- What it is
- A bar chart estimating dealer delta at each strike, and the futures hedge today's change implies.
- Data it uses
- NSE option chain: open interest, today's buildup and implied volatility per strike; spot; the lot size. Delta is computed with Black-Scholes. An estimate.
- Covers
- NIFTY, BANKNIFTY, FINNIFTY, MIDCPNIFTY and NIFTY NEXT 50
- Updates
- Through the session as NSE's data arrives (15 minutes delayed); past sessions can be opened, and today can be replayed minute by minute
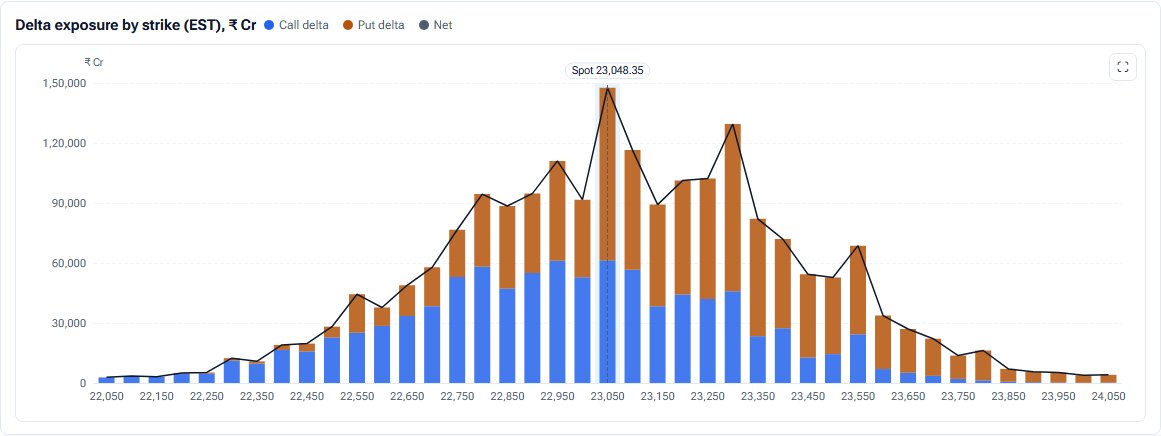
What the chart shows
- Stacked bars by strike, call delta in blue and put delta in orange, with net delta as a line and spot dashed.
- Cards: dealer delta change today, the futures hedge it implies (dealers sell or buy futures, about N lots), the strike with the biggest shift, and the whole book.
- Unit in ₹ crore or lots, and a trend through the session under More detail.
How it is worked out
DEX at a strike = dealer contracts × delta × lot size × spot, in ₹ crore; in lots it is dealer contracts × delta. Delta comes from Black-Scholes on each leg's IV, on the same dealer assumption as gamma exposure.
How to read it
The lead number is today's change, because the whole book is almost always large and positive and mostly tracks how much OI is open. If today left dealers longer delta, they would sell futures to stay flat; the lot count hints at the size of that flow.
Controls
- Session: today, or a stored past session
- Expiry: one at a time
- Strikes: around the money, or a custom range
- Unit: ₹ crore or lots
- Replay: any minute of today's session
Keep in mind
An estimate (EST) built on a stated guess about which side dealers hold. Treat it as a rough map, not a fact about any strike.
Delta exposure questions
What is delta exposure?
An estimate of the net delta option dealers hold at each strike, in rupees or lots, and so how much futures they would trade to stay hedged.
Why lead with today's change?
On the usual dealer assumption the whole book is always large and positive. The change since the open is the part that says something about today.
How is it different from GEX?
Delta exposure is the hedge dealers hold now; gamma exposure is how fast that hedge changes as the index moves.
Related tools and guides
Gamma exposure
Estimated dealer gamma at every strike in ₹ crore per 1% move, the net GEX regime and the flip level, worked out from the option chain.
Change in OI
Today's change in call and put open interest at every strike: who is writing, who is covering, and what changed in the last 15, 30 or 60 minutes.
Futures buildup
The index future against its VWAP, and open interest added in each bucket coloured as long buildup, short buildup, short covering or long unwinding.
All Pulse charts
Every chart in Pulse with a screenshot and what it tells you.
Educational analytics only: not investment advice. You are responsible for your own trading decisions.